NNN Lease Recovery Analysis: How to Calculate Expense Pass-Throughs
Expense recoveries are the share of operating expenses that tenants reimburse to the landlord under the lease. In a triple net (NNN) lease the tenant pays its pro-rata share of taxes, insurance, and CAM; under a base year stop only increases above the base year; under modified gross a negotiated split. Solsten CRE models all three per tenant with occupancy-aware pools.
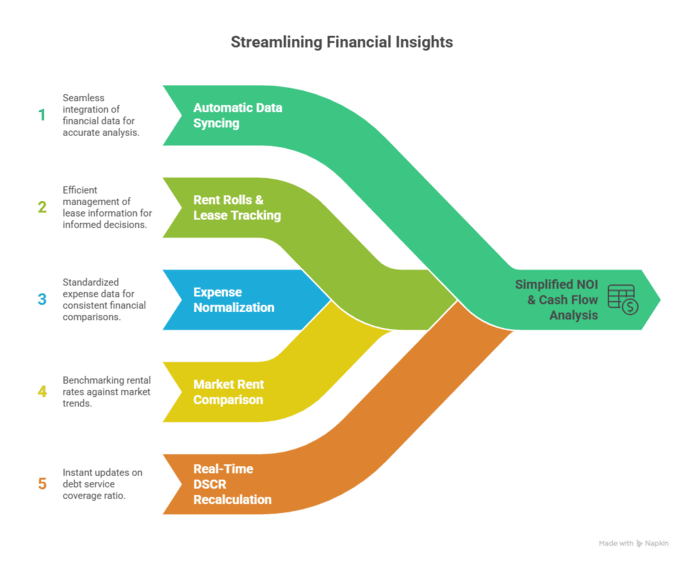
If you own or underwrite commercial real estate, operating expense recoveries are one of the biggest drivers of your bottom line. A property with identical NOI can produce wildly different cash flows depending on how the leases handle expense pass-throughs.
This guide breaks down the three main recovery structures, walks through real calculation examples, and shows where most analysts make mistakes.
What Are Expense Recoveries?
In commercial real estate, expense recoveries (also called CAM reimbursements, operating expense pass-throughs, or simply “recoveries”) are the portions of operating expenses that tenants pay back to the landlord.
The fundamental question is simple: who pays for what?
- The landlord always pays the bills (insurance, taxes, maintenance, etc.)
- The lease determines how much tenants reimburse
How this split works depends entirely on the lease recovery structure.
The Three Recovery Structures
1. Net Lease (NNN / Triple Net)
In a Triple Net (NNN) lease, the tenant reimburses their pro-rata share of all operating expenses — property taxes, insurance, and common area maintenance (CAM).
The math:
Example:
- Building: 50,000 SF
- Tenant A: 10,000 SF (20% of building)
- Total operating expenses: $500,000/year
- Tenant A reimburses: $500,000 × 20% = $100,000/year
In a multi-tenant building the share is usually computed on rentable area measured under the BOMA standard for the property type (ANSI/BOMA Z65.1 for office, Z65.2 for industrial, Z65.5 for retail), so confirm which measurement standard the lease cites before you trust the denominator.
NNN leases are common in single-tenant retail, industrial, and some office properties. The landlord’s exposure to rising expenses is minimal because the tenant absorbs the increases.
Why investors love NNN: Your NOI is essentially your base rent. Operating expense increases don’t eat into your returns — they’re the tenant’s problem.
The catch: NNN tenants know they’re absorbing expenses, so they negotiate lower base rents. And if expenses spike unexpectedly, you may face pushback or tenant credit issues.
2. Base Year Stop
A Base Year Stop lease sets a baseline of operating expenses in the first year of the lease. The tenant only reimburses expenses that exceed the base year amount.
The math:
If current expenses are below the base year, the tenant pays nothing.
Example:
- Base Year (Year 1) OpEx: $10.00/SF
- Year 3 OpEx: $11.50/SF
- Tenant area: 10,000 SF of 50,000 SF building
- Tenant Recovery: ($11.50 − $10.00) × 10,000 = $15,000
- Landlord absorbs: The original $10.00/SF forever
Base Year Stop is the most common structure in multi-tenant office buildings. It provides tenants with predictable occupancy costs in year one while protecting the landlord from expense inflation over time.
The risk for landlords: If you sign a lease during a year with abnormally high expenses (say, a major insurance spike), the base year is set artificially high. The tenant might never reimburse anything because actual expenses never exceed the elevated base.
Pro tip: Some landlords negotiate a “grossed-up” base year — adjusting the base year expenses to reflect full occupancy. This prevents a half-empty building from setting an artificially low base.
3. Modified Gross
A Modified Gross lease splits expenses between landlord and tenant, but with fixed amounts or percentages rather than dollar-for-dollar pass-through.
Common structures include:
- Tenant pays a fixed $/SF CAM charge (regardless of actual costs)
- Landlord covers base building expenses, tenant covers suite-level
- Percentage split — e.g., landlord pays 60%, tenant pays 40%
Example (Fixed CAM):
- Tenant’s fixed CAM charge: $4.00/SF
- Tenant area: 10,000 SF
- Tenant pays: $40,000/year regardless of actual expenses
- If actual CAM is $5.00/SF, landlord absorbs the $1.00/SF difference
- If actual CAM drops to $3.50/SF, landlord pockets the $0.50/SF surplus
Modified Gross leases are common in Class B office, creative office, and mixed-use properties. They give both parties some predictability.
Common Underwriting Mistakes
Mistake 1: Ignoring Recovery Structure in Your Proforma
This is the most expensive mistake in CRE underwriting. You model operating expenses growing at 3% annually — but if you’re running NNN leases and not modeling the corresponding recovery income, your NOI is understated by potentially hundreds of thousands of dollars.
The fix: Always model recovery income alongside operating expenses. When you project expenses growing, you need to project recoveries growing proportionally.
Mistake 2: Not Grossing Up Base Year for Occupancy
If your building was 60% occupied in the base year, your base year expenses are artificially low (less wear, lower variable costs). When the building leases up to 95%, expenses increase — but that increase includes the natural cost of higher occupancy, not just inflation.
A proper base year “gross-up” adjusts variable expenses to reflect stabilized occupancy:
This is a lease-reading adjustment, not a software switch. In Solsten, gross-up is a setting on the recovery structure: Modified Gross pools carry a gross-up percentage (typically 95%), while NNN and Base Year Stop pools bill on actual expense amounts, so a Base Year Stop pool recovers the increase over the base year as it actually occurred.
Mistake 3: Treating All Expenses as Recoverable
Not all operating expenses are recoverable from tenants:
| Typically Recoverable | Typically NOT Recoverable |
|---|---|
| Property taxes | Capital expenditures |
| Insurance | Leasing commissions |
| CAM / Maintenance | Tenant improvements |
| Utilities (common area) | Debt service |
| Management fees | Depreciation |
| Landscaping / Snow removal | Legal fees (landlord) |
Your recovery calculations should only include operating expenses, never capital costs or financing-related items.
Mistake 4: Forgetting Vacancy Impact on Recoveries
In a 100,000 SF building with 85% occupancy, your recoverable base is only 85,000 SF — not 100,000 SF. The landlord absorbs the pro-rata share of expenses for vacant space.
This creates a compounding problem: vacancy reduces your rental income AND your recovery income simultaneously.
This is exactly why commercial real estate investors monitor occupancy so closely. Below a certain breakeven threshold, expenses exceed income.
Recovery Analysis in Practice
Building a proper recovery analysis requires tracking several moving pieces simultaneously:
- Expense categorization — Which expenses are recoverable vs. non-recoverable?
- Recovery structure per tenant — NNN, Base Year Stop, or Modified Gross?
- Base year values — What was the expense baseline when each lease started?
- Occupancy over time — How does changing occupancy affect recovery pools?
- Expense inflation — How are expenses projected to grow?
- Lease rollover — When leases expire, how do new lease terms affect recoveries?
In Excel, this typically means maintaining a matrix of expenses × tenants × years — dozens of worksheets that break when a single lease changes.
Professional underwriting tools handle this automatically. In Solsten, for example, you set each expense’s recovery type and percentage, assign recovery structures to each tenant, and the engine calculates the recovery pool across your entire hold period — including projected vacancy, tenant lifecycle events, and expense inflation.
How Recovery Type Affects Property Valuation
The recovery structure directly impacts how you value a property:
NNN properties trade at lower cap rates (higher prices) because the income stream is more predictable and the landlord has less expense risk. A single-tenant NNN retail property might trade at a 5.5% cap rate. The Boulder Group publishes quarterly net lease cap rate research by sector if you want a current market read.
Full-service gross properties (landlord pays everything) trade at higher cap rates because the landlord bears all expense risk. The same property type might trade at a 7%+ cap rate.
Base Year Stop properties fall in between — the landlord has limited downside (base year expenses) with upside protection as tenants reimburse above-base increases.
When comparing properties with different recovery structures, you must normalize to the same basis. A $1,000,000 NOI from a NNN property is worth more than $1,000,000 NOI from a gross property because the NNN income is more durable.
Key Takeaways
-
Recovery structure is as important as base rent when underwriting a commercial property. Two identical base rents can produce very different cash flows depending on who pays operating expenses.
-
Always model recovery income in your proforma. Failing to account for tenant reimbursements will dramatically understate your returns.
-
Base Year Stop leases require careful base year selection. Abnormal expense years (high or low) distort the recovery calculation for the entire lease term.
-
Vacancy hurts twice — lost rent AND lost recovery income. Factor this into your breakeven occupancy analysis.
-
Professional tools eliminate the complexity. When you’re tracking 10 tenants with different recovery structures across a 10-year hold, manual Excel modeling becomes error-prone and time-consuming.
Related Articles
- How to Read & Analyze a T-12 Operating Statement — Verify historical expenses before building your recovery model
- Due Diligence Checklist for CRE — Recovery structure review is a critical diligence step
- Best ARGUS Alternatives for CRE Teams — How recovery modeling (NNN, Base Year Stop, Modified Gross) compares across underwriting platforms
Eric Davis is the founder of Nordic Real Estate Services and creator of Solsten, a professional CRE analysis platform with automated recovery calculations, ML-powered forecasting, and ARGUS-grade proforma modeling. Learn more about recovery types →
Frequently asked questions
- What are expense recoveries in commercial real estate?
- The portion of operating expenses that tenants reimburse to the landlord, also called CAM reimbursements or pass-throughs. The landlord pays the bills; the lease determines how much each tenant pays back and under which structure: NNN, base year stop, or modified gross.
- How is an NNN recovery calculated?
- Tenant recovery equals total operating expenses multiplied by the tenant's share of the building, usually tenant rentable square feet divided by building rentable square feet. A 10,000 square foot tenant in a 50,000 square foot building with $500,000 of operating expenses reimburses $100,000 per year.
- What is a base year stop lease?
- The tenant reimburses only the expenses that exceed the base year amount set in the first year of the lease, pro rata to their square footage. If base year expenses are $10.00 per square foot and year three expenses are $11.50, a 10,000 square foot tenant pays $15,000, and the landlord absorbs the original $10.00 per square foot for the life of the lease.
- What is a modified gross lease?
- A split of expenses between landlord and tenant using fixed amounts or percentages rather than dollar-for-dollar pass-through: a fixed per-square-foot CAM charge, landlord covering base building costs while the tenant covers suite-level costs, or a stated percentage split. Common in Class B office, creative office, and mixed-use properties.
- Which operating expenses are not recoverable from tenants?
- Capital expenditures, leasing commissions, tenant improvements, debt service, depreciation, and the landlord's own legal fees. Recoveries should include only operating expenses such as taxes, insurance, CAM, common-area utilities, management fees, landscaping, and snow removal.
- How does vacancy affect expense recoveries?
- Only occupied space contributes to the recovery pool. In a 100,000 square foot building at 85 percent occupancy the recoverable base is 85,000 square feet, and the landlord absorbs the vacant share of expenses. Vacancy therefore cuts rental income and recovery income at the same time.
- Why do NNN properties trade at lower cap rates?
- Because the income is more predictable: the tenant absorbs expense increases, so NOI is essentially base rent. A single-tenant NNN retail property might trade near a 5.5 percent cap rate while a comparable full-service gross property, where the landlord bears all expense risk, might trade at 7 percent or higher.
Try Solsten Free
See everything we discussed in action — no credit card required.
Start Your Free AnalysisRelated Articles
How to Calculate Operating Expenses for Commercial Real Estate
A complete guide to CRE operating expenses — categories, fixed vs. variable, below-the-line items, and how expense modeling affects your NOI, DSCR, and investment returns.
What Is a T12 in Real Estate? How to Read a T-12 Report
A T12 is twelve months of a property's actual income and expenses. How to read a T-12 report line by line, spot red flags, and turn it into your underwriting.
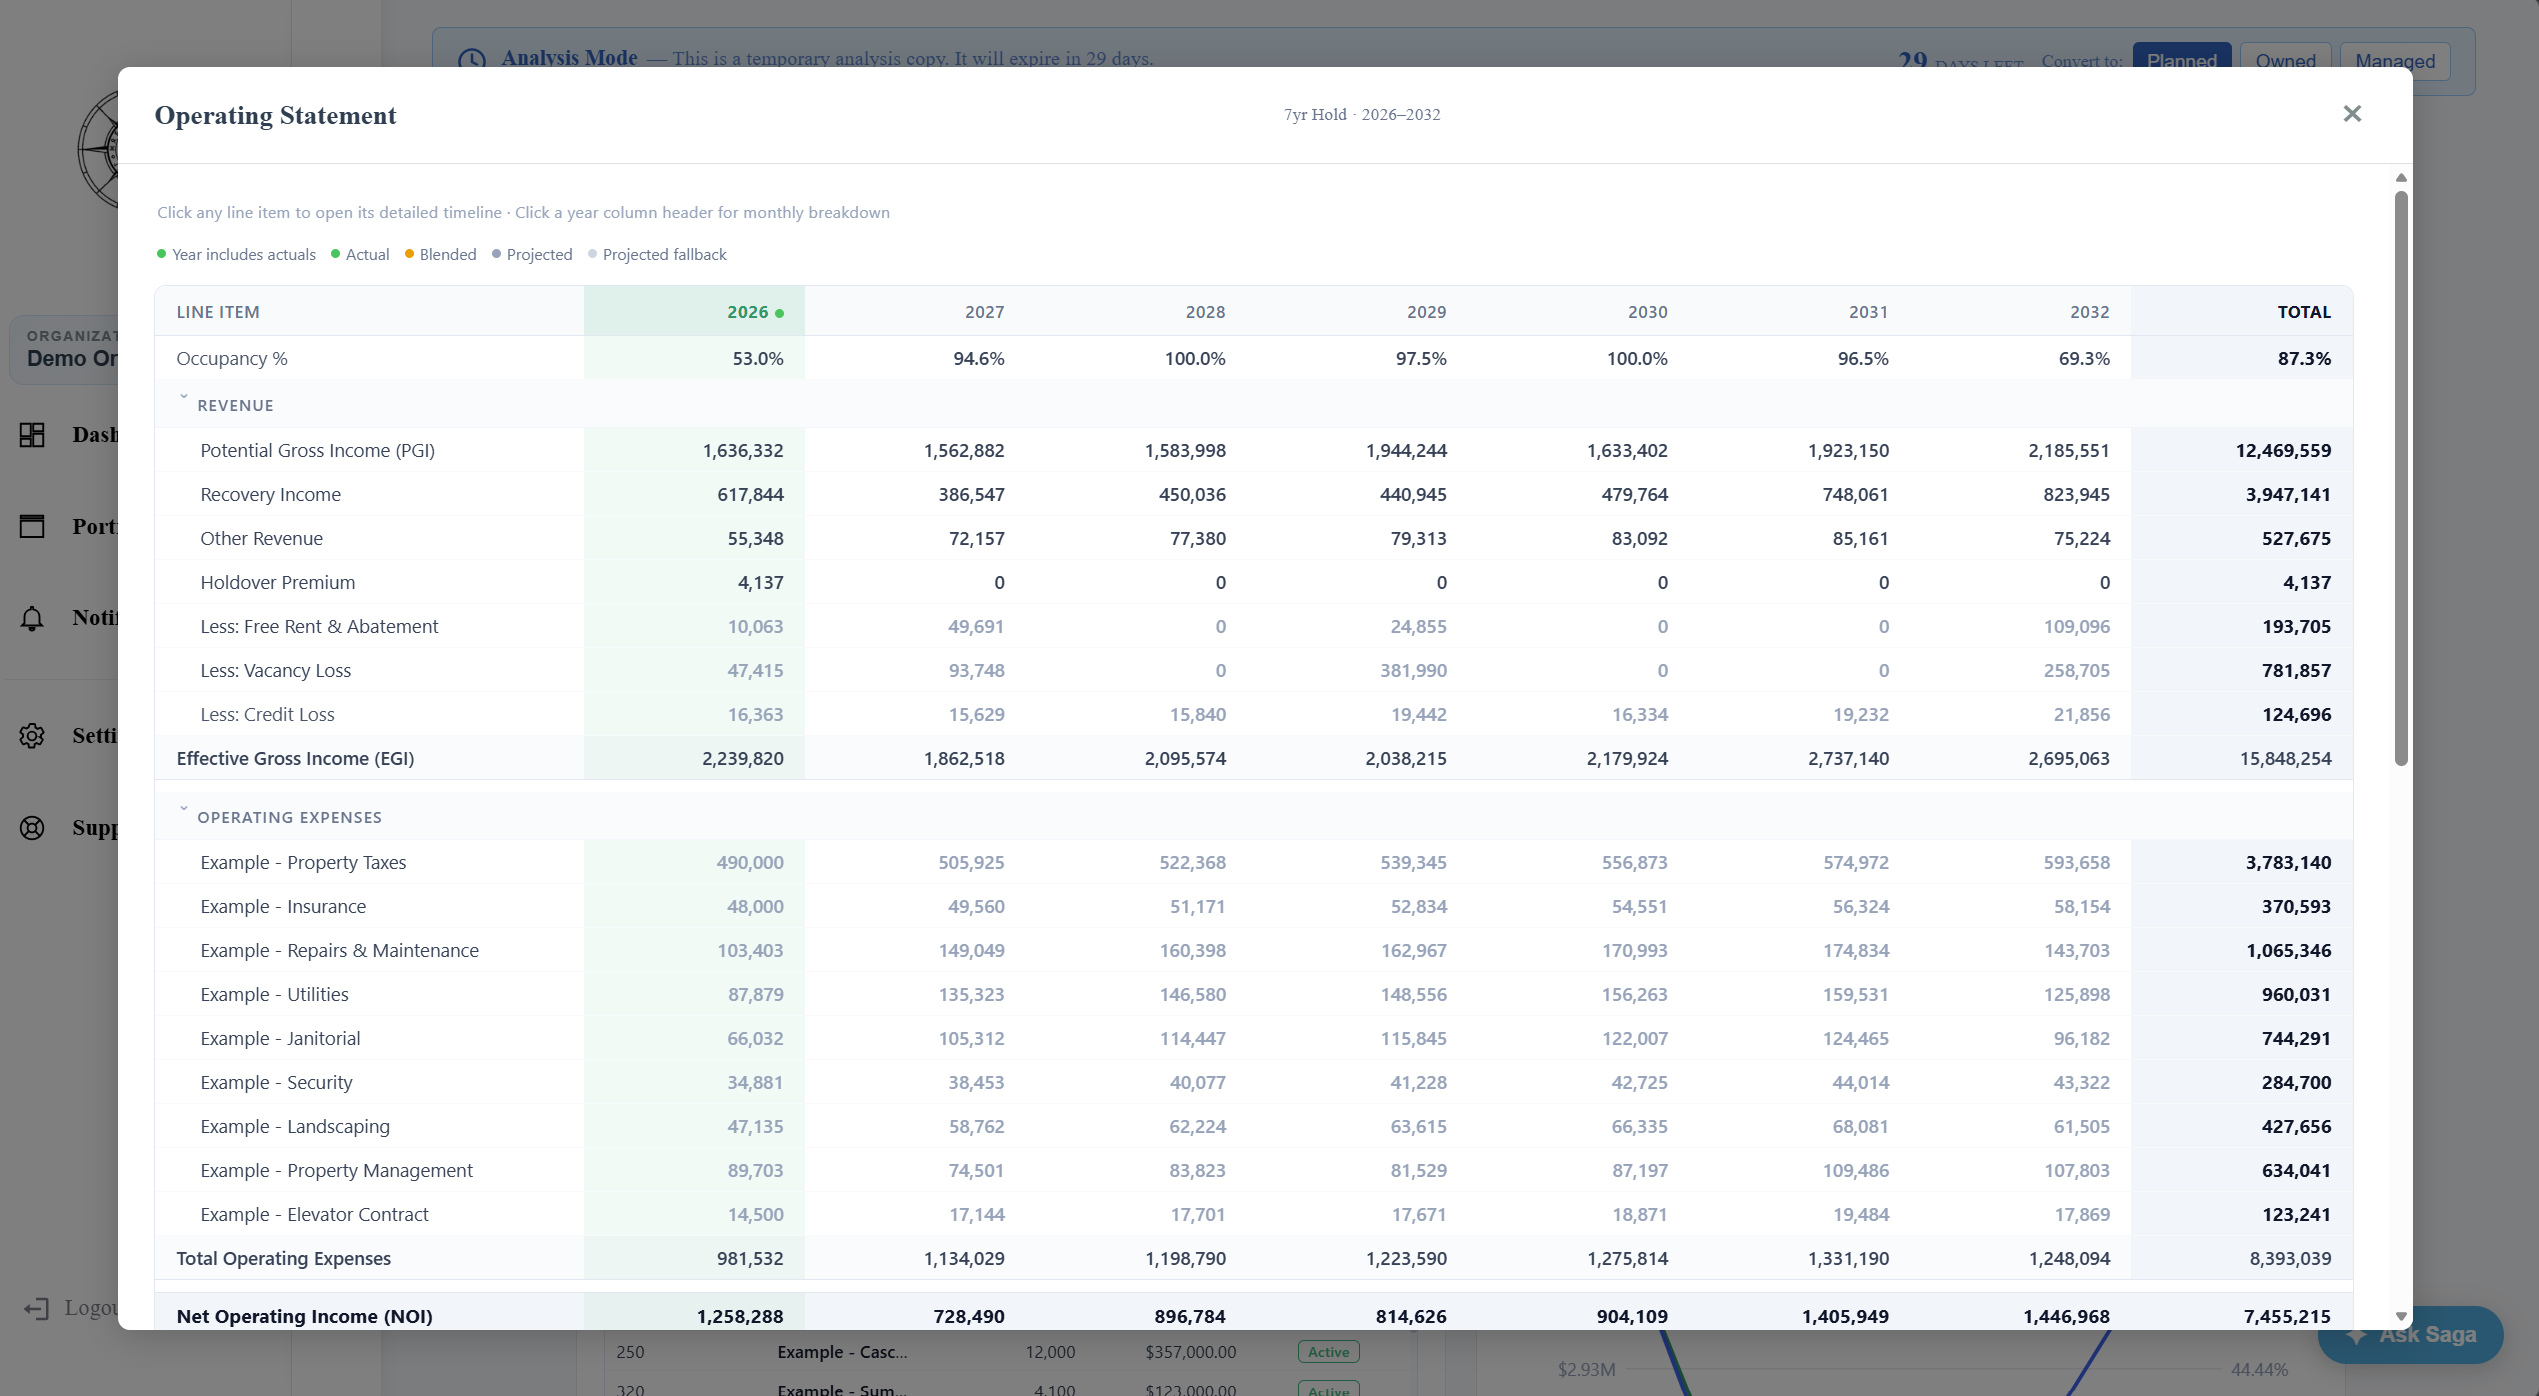
Commercial Real Estate Cash Flow Analysis: From NOI to Cash-on-Cash
Commercial real estate cash flow, step by step: PGI to distributable cash, a worked office example with debt service and reserves, why monthly matters, and five mistakes to avoid.